Long-term care is one of the biggest financial risks Singapore families face, yet it is often overlooked until a loved one becomes seriously ill or loses the ability to care for themselves.
To address the rising cost of long-term care, Singapore's national long-term care insurance scheme, CareShield Life, is undergoing its first major review since its launch in 2020.
From 2026, policyholders will enjoy higher monthly payouts, with benefits increasing at a faster rate. However, premiums will also rise to support these enhanced benefits.
So, what exactly is changing, who will be affected, and is CareShield Life enough to cover the cost of long-term care?
CareShield Life is Singapore's national long-term care insurance scheme, launched on 1 October 2020. It provides monthly cash payouts to individuals who become severely disabled, for as long as their disability persists.
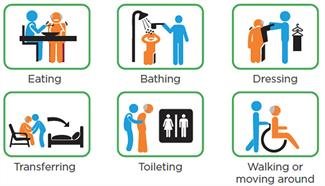
To qualify for a claim, an individual must be assessed by an MOH-accredited assessor as being unable to perform at least 3 out of the 6 Activities of Daily Living (ADLs):
Unlike hospitalisation insurance, CareShield Life is not designed to cover medical bills or short-term illnesses. Instead, it provides financial support when someone requires long-term assistance with everyday activities, whether through home care, day care services or nursing home facilities.
CareShield Life coverage is automatic for Singapore Citizens and Permanent Residents born in 1980 or later, starting from age 30. Participation is compulsory, even for individuals with pre-existing medical conditions.
Those born in 1979 or earlier can choose to join the scheme voluntarily. However, from 1 January 2026, only individuals who do not have a pre-existing disability will be allowed to enrol.
Premiums are payable annually until age 67 and can be fully paid using MediSave. Once a successful claim is made, future premiums are waived. Importantly, individuals will not lose their CareShield Life coverage simply because they are unable to afford their premiums.
The 2026 enhancements follow the recommendations of the independent CareShield Life Council, which were accepted by the Government in August 2025.
There are three major changes worth understanding.
1. Monthly Payouts Increase at 4% Annually, Up From 2%
The most significant enhancement is the increase in the annual growth rate of CareShield Life payouts.
Previously, monthly payouts increased by 2% annually. From 2026 to 2030, this growth rate will double to 4% per year.
The revised monthly payouts are:
Year of Claim Monthly Payout
2026 $689
2027 $717
2028 $745
2029 $775
2030 $806
To put this into perspective, someone who makes a successful claim in 2030 would receive $806 per month under the enhanced scheme, compared with approximately $731 under the previous 2% growth rate.
Your monthly payout increases annually until you reach age 67 or make a successful claim, whichever comes first.
Once a claim is made, the monthly payout is fixed for as long as you remain severely disabled. The impact of this increase becomes even more significant over the long term.
According to MOH's illustration, assuming the 4% annual growth rate continues until age 67, an individual who becomes severely disabled at age 67 could receive approximately $2,324 per month under the enhanced scheme, compared with $1,248 under the previous payout structure.
However, it is important to note that this illustration assumes the 4% growth rate continues beyond 2030. Any subsequent increases will depend on future reviews.
2. Premiums Increase
Higher payouts naturally come with higher insurance costs.
To fund the enhanced benefits, CareShield Life premiums will undergo a one-time increase in 2026, followed by annual increases of 4%.
However, the Government has committed more than $570 million in additional premium support over the next five years, on top of existing subsidies. The actual impact will vary depending on your age, gender, age at enrolment and applicable subsidies.
For an accurate estimate, refer to your MOH or CPF notification or use the official CareShield Life premium checker.
While the 2026 enhancements are certainly welcome, there is an important question that Singaporeans should consider:
Is $689 a month enough to pay for long-term care?
The reality is that CareShield Life is designed to provide a basic financial safety net, rather than cover the full cost of long-term care.
According to Singlife, the enhanced $689 monthly payout in 2026 covers only around 23% of the average long-term care costs reported by caregivers.
Actual expenses vary depending on the type of care required. Home-based caregiving, day care services and nursing home accommodation can have very different costs.
For families requiring professional assistance or round-the-clock care, the monthly expenses can quickly exceed the CareShieldlife payout.
This leaves a significant financial gap that individuals and their families may need to fund themselves.
This is where CareShield Life supplements come in.
These are private insurance plans offered by various insurers to complement the basic protection provided by CareShield Life.
Depending on the insurer and plan selected, supplements can provide additional benefits such as:
• Higher monthly payouts: Additional monthly benefits, commonly ranging from $200 to $5,000.
• Earlier claim eligibility: Some plans allow claims when an individual is unable to perform just 1 or 2 ADLs, rather than waiting until 3 ADLs.
• Lump-sum benefits: Certain plans provide an additional lump-sum payout upon a successful claim.
• Escalating benefits: Some plans offer increasing monthly payouts over time to help offset rising long-term care costs.
Another advantage is that individuals can use up to $600 annually from their MediSave account to pay for CareShield Life Supplement premiums, with any remaining amount payable in cash.
However, premiums and benefits differ significantly across insurers. They depend on factors such as age, gender, coverage amount and the type of benefits selected.
Generally, purchasing additional coverage at a younger age is more affordable than waiting until your 50s or 60s.
CareShield Life Is the Foundation, Not the Entire Solution
The 2026 CareShield Life enhancements are a positive development for Singaporeans.
Monthly payouts will grow faster at 4% annually until 2030, while the Government is committing more than $570 million in additional premium support to cushion the increase in premiums.
However, the fundamental purpose of CareShield Life remains unchanged: to provide a basic financial safety net against severe disability.
With the cost of long-term care potentially running into thousands of dollars each month, relying solely on the national scheme may leave individuals and their families exposed to a substantial financial shortfall.
Think of CareShield Life as the foundation of your long-term care protection. The next step is to determine whether that foundation is sufficient for your needs.
ertertyt ytr yty tryrtsy rt yrt ysrtysrt aer y